All Categories
Featured
Life Insurance Options for Veterans
1 Investopedia - How Whole Life Insurance Functions. Upgraded May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance coverage: Pros, cons & who it's best for. Updated March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance? (& How Does it Work?) Updated December 18, 2024.
Accessed June 18, 2026. 4 Forbes - What Varies Life Insurance Coverage? Upgraded November 26, 2024. . Accessed June 18, 2026. Material within this short article is offered for basic informative purposes and is not offered as tax, legal, health, or monetary advice for anyone or for any particular scenario.
For total information, consisting of schedule and expenses of Aflac insurance, please contact your regional Aflac agent/producer. Aflac life prepares A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400.
Affordable Term Life Insurance Quotes Today
In Delaware, Policy A68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Not available in Virginia. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York City, Policy: NYQ60100M. Not offered in Virginia. In AR, DE, ID, OKAY and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22.

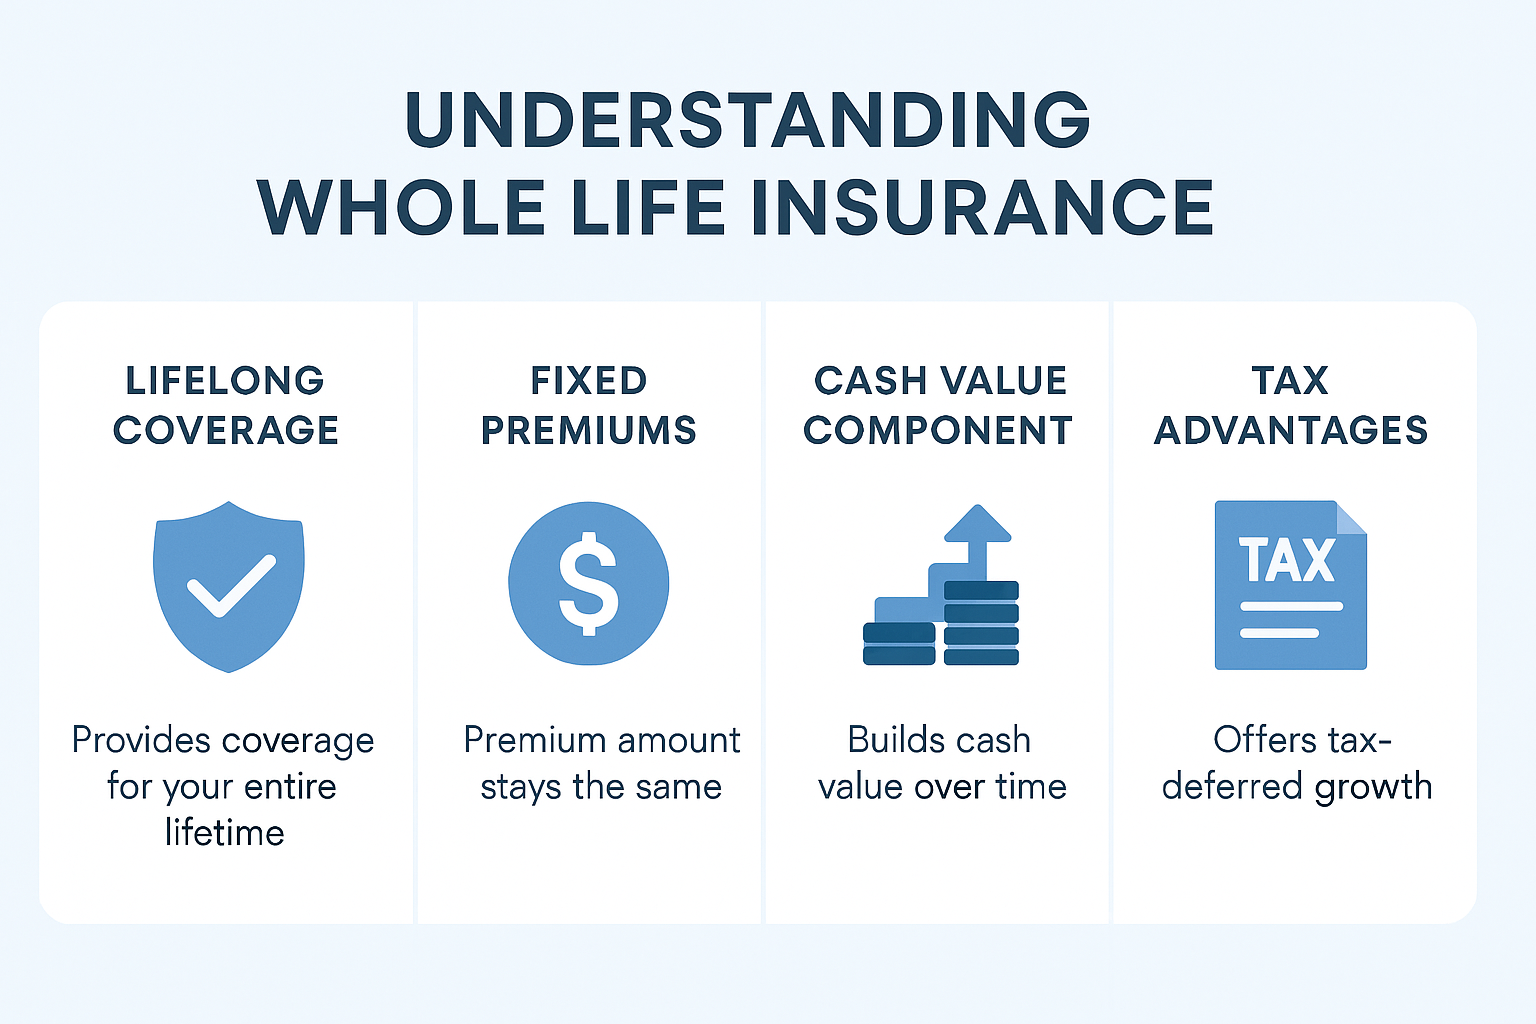
In this short article, we discuss what whole life insurance is and compare it to call life insurance coverage, as well as universal life and variable life insurance coverage. Entire life insurance is one kind of permanent insurance coverage and is really various from term life insurance coverage, which offers coverage for a specified period just and does not build cash value. If term life insurance is the most common type of life insurance coverage, whole life insurance coverage is the oldest kind of permanent life insurance coverage.
The bigger your money value, the larger the loan you can take. You can utilize your money worth to supplement your other retirement earnings. Entire life insurance coverage is the only type of life insurance that guarantees of the following: The death advantage won't decrease The policy won't end as long as premiums are paid Your premiums will not
Medicare in Chula Vista
go up Your costs will never ever increase The insurance provider ensures that the cash worth of your whole life insurance policy will grow gradually. figure out just how much your money worth need to grow based on existing rate of interest, which, obviously, differ gradually. enable you to invest funds in policy subaccounts, comparable to shared funds. Your money value will increase orreduce, depending upon the efficiency of these subaccounts. What takes place if efficiency of the money worth of your universal or variable life policy drops? Who needs to ante up more exceptional to keep your policy in force? You do. Neither option is good. If you have an entire life policy, you will not have to make those awful options. The premium, cash value, and survivor benefit are all ensured. And did you know you can find out exactly what your surefire premium, money worth and survivor benefit will be at any moment before you decide if it makes sense to begin a whole life policy? Simply ask for a FREE, no-obligation Analysis here to take the first action. In a manner, it resembles getting an earnings tax refund. Now, dividends are not ensured. It's possible an insurer might have a horrible, awful, no good, very bad year . In truth, that's what the company plans for. And every year that'smuch better than they planned, they can pay a dividend. Get Your FREE Report! Get instant access to the FREE 18-page Unique Report that reveals how super-charged dividend paying entire life insurance coverage lets you bypass Wall Street, fire your banker, and take control of your financial future. You get to tell the insurance coverage business what to do with your dividend. and this simply may be the neatest thing given that cupcakesyou can have them utilize your dividend to buy more insurance coverage for you insurance you'll never ever need to pay another premium for again. Think of that! You can purchase extra insurance that's paid up, suggesting no more premiums will be due on that additionever. If that reminds you of the 8th marvel of the worldcompound interestthat's due to the fact that the concept is exactly the exact same. Only paid up whole life insurance additions build both your policy's cash value and your survivor benefit. You can find out more here about dividend-paying entire life insurance, which many individuals find especially exciting. Term life insurance premiums go upsometimes drasticallywith every new term, because much of the cost of insurance coverage is based upon how likely you are to die at a provided age, and as you age, that probability goes up. Universal and variable insurance coverage premiums can increase, tooagain, in some cases drasticallyif cash value drops dueto low rates of interest or poor financial investment efficiency. You may be asking, "If it costs more to insure my life with every death year, how can a life insurance coverage business guarantee my premiums will never ever go up?" The answer is elegantly simpleand it assists describe why whole life insurance coverage is more costly than term insurance in the early years of the policy.

Latest Posts
Evaluating PPO vs HMO Health Insurance Plans
How to Enroll in 2026 Medicare Part D

Choosing Between PPO Vs HMO Medical Plans