All Categories
Featured
Affordable 2026 Term Life Insurance Rates Today
Table of Contents
With entire life insurance coverage, you get to choose how your dividends will be utilized. Here are a few of the choices: Purchase additional insurance, which can increase your survivor benefit and collected cash value quicker than your policy's original warranties. When you utilize your dividend to acquire extra insurance coverage, it sets a new level of assurance from which the policy's values can't fall from one year to the next Minimize the amount of premium you owe each year.
Your Northwestern Mutual monetary consultant can assist you figure out the best alternative for you. Your policy will collect money value that's guaranteed to grow with time and isn't tied to the stock marketmeaning it will not decrease after a drop in stock prices. And if you pick to utilize dividends to purchase additional insurance, your accumulated cash worth and survivor benefit can increase even quicker, compounding over time.
When accessing your cash value, you have a few options to consider. You can take a loan versus your policy from the insurer. Repayment of the loan is versatile, however interest will accrue. If you pass away with a loan against the policy, your death advantage will be decreased by the quantity of the loan.
Cheap Health Insurance Quotes for Families
This might be a good option if you have a monetary emergency or for bigger, infrequent requirements, such as redesigning a home. When you surrender your policy, you'll no longer have your insurance coverage. Oftentimes, when individuals need to access their money worth and no longer need their full survivor benefit, they surrender a part of their policy.
This can also be helpful from a tax viewpoint. That's because when you give up a policy, you'll owe common income tax on any money value above cash that you've paid in (or "basis"). In this case, you can take all the cash value in your policy, however you likewise give up all your life insurance coverage.
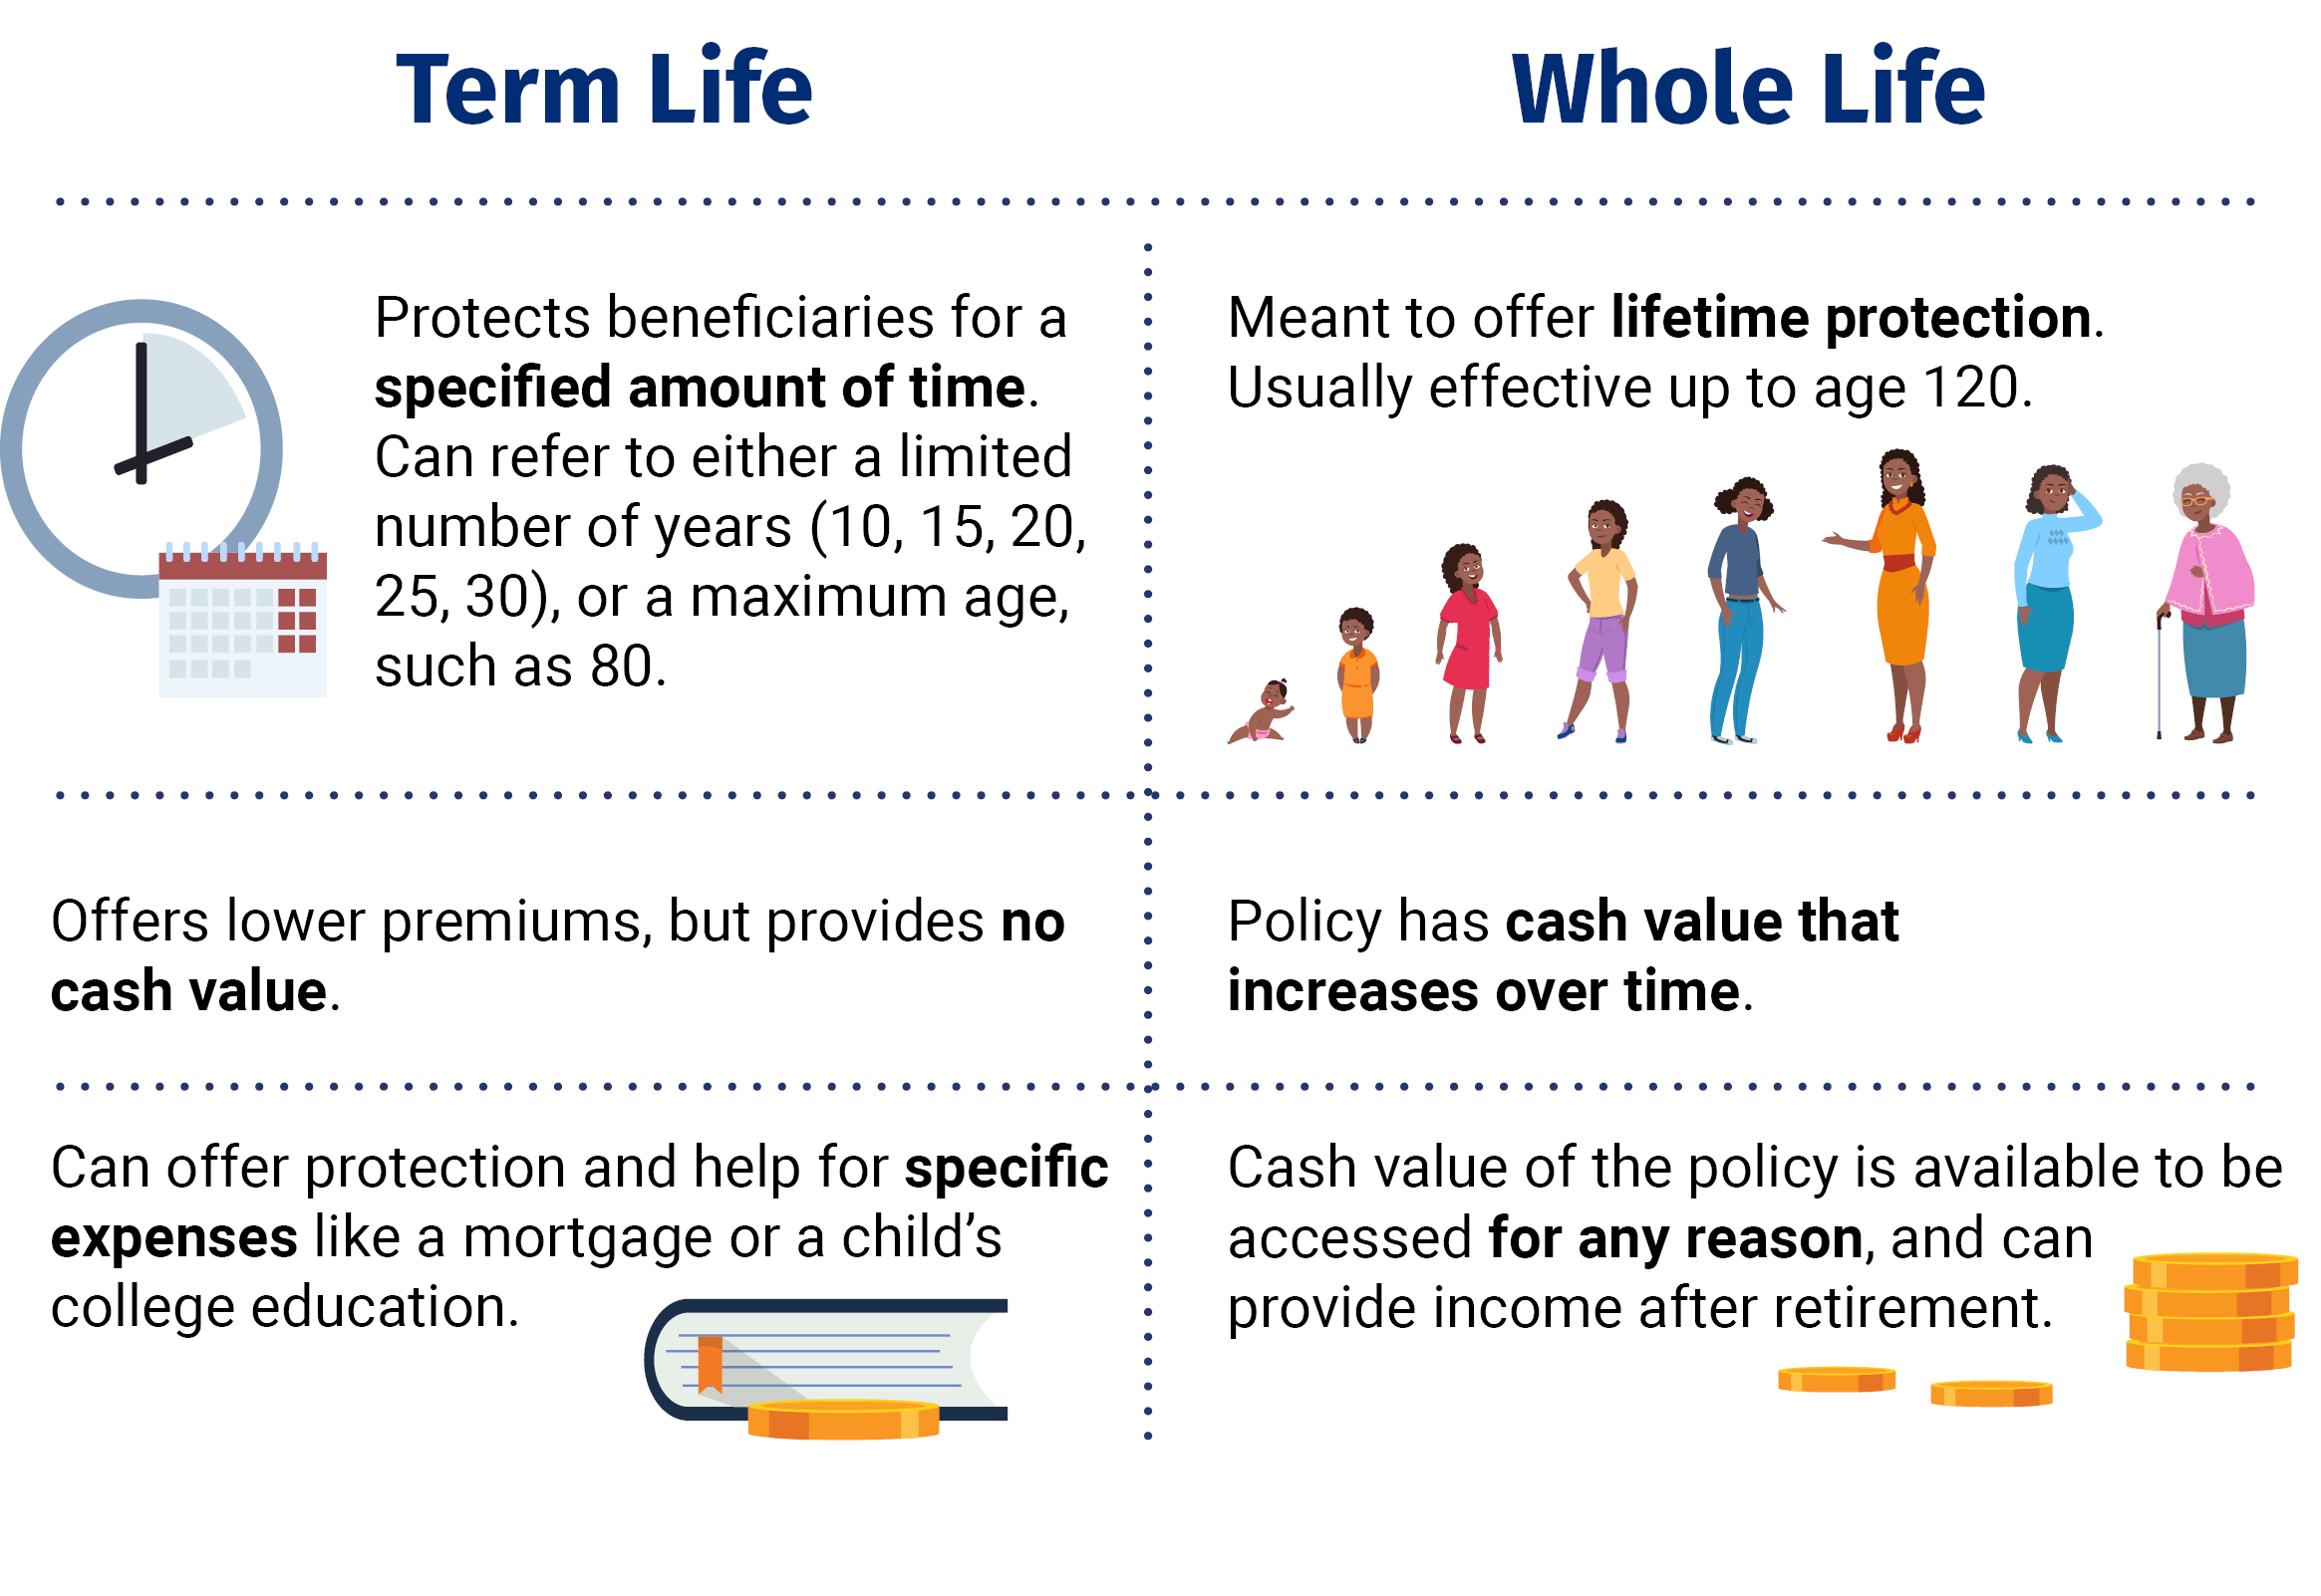
If you're thinking about tapping into your cash worth, your monetary consultant can help you analyze the very best choices for your situation. If you have an optional waiver of premium rider on your policy, the business will pay your life insurance premiums if you become handicapped. Throughout this time, your money value will continue to grow without you owing any money for your policy.
Affordable Term Life Insurance Quotes Today
This advantage suggests that modifications in your health won't affect your ability to get more insurance coverage down the roadway. Whole life insurance can work together with other financial tools like financial investments and deferred earnings annuities in a diverse technique to retirement cost savings. A research study by EY discovered that retirement techniques including permanent life insurance coverage and deferred earnings annuities stood out compared to investment-only techniques.
, particularly during down markets.
Otherwise, if you access those accounts while they are down, you 'd essentially be selling at a loss.
How Whole Life Insurance Works. Accessed March 26, 2026. Material within this post is supplied for general educational functions and is not supplied as tax, legal, health, or monetary guidance for any individual or for any particular scenario.
The Mechanics of Whole Life Coverage
Aflac life prepares A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York City, Policies NY68200, NY68300 and NY68400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. In Delaware, Policy A68100.
B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In New York, Policy: NYQ60200M. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID.

Latest Posts
Evaluating PPO vs HMO Health Insurance Plans
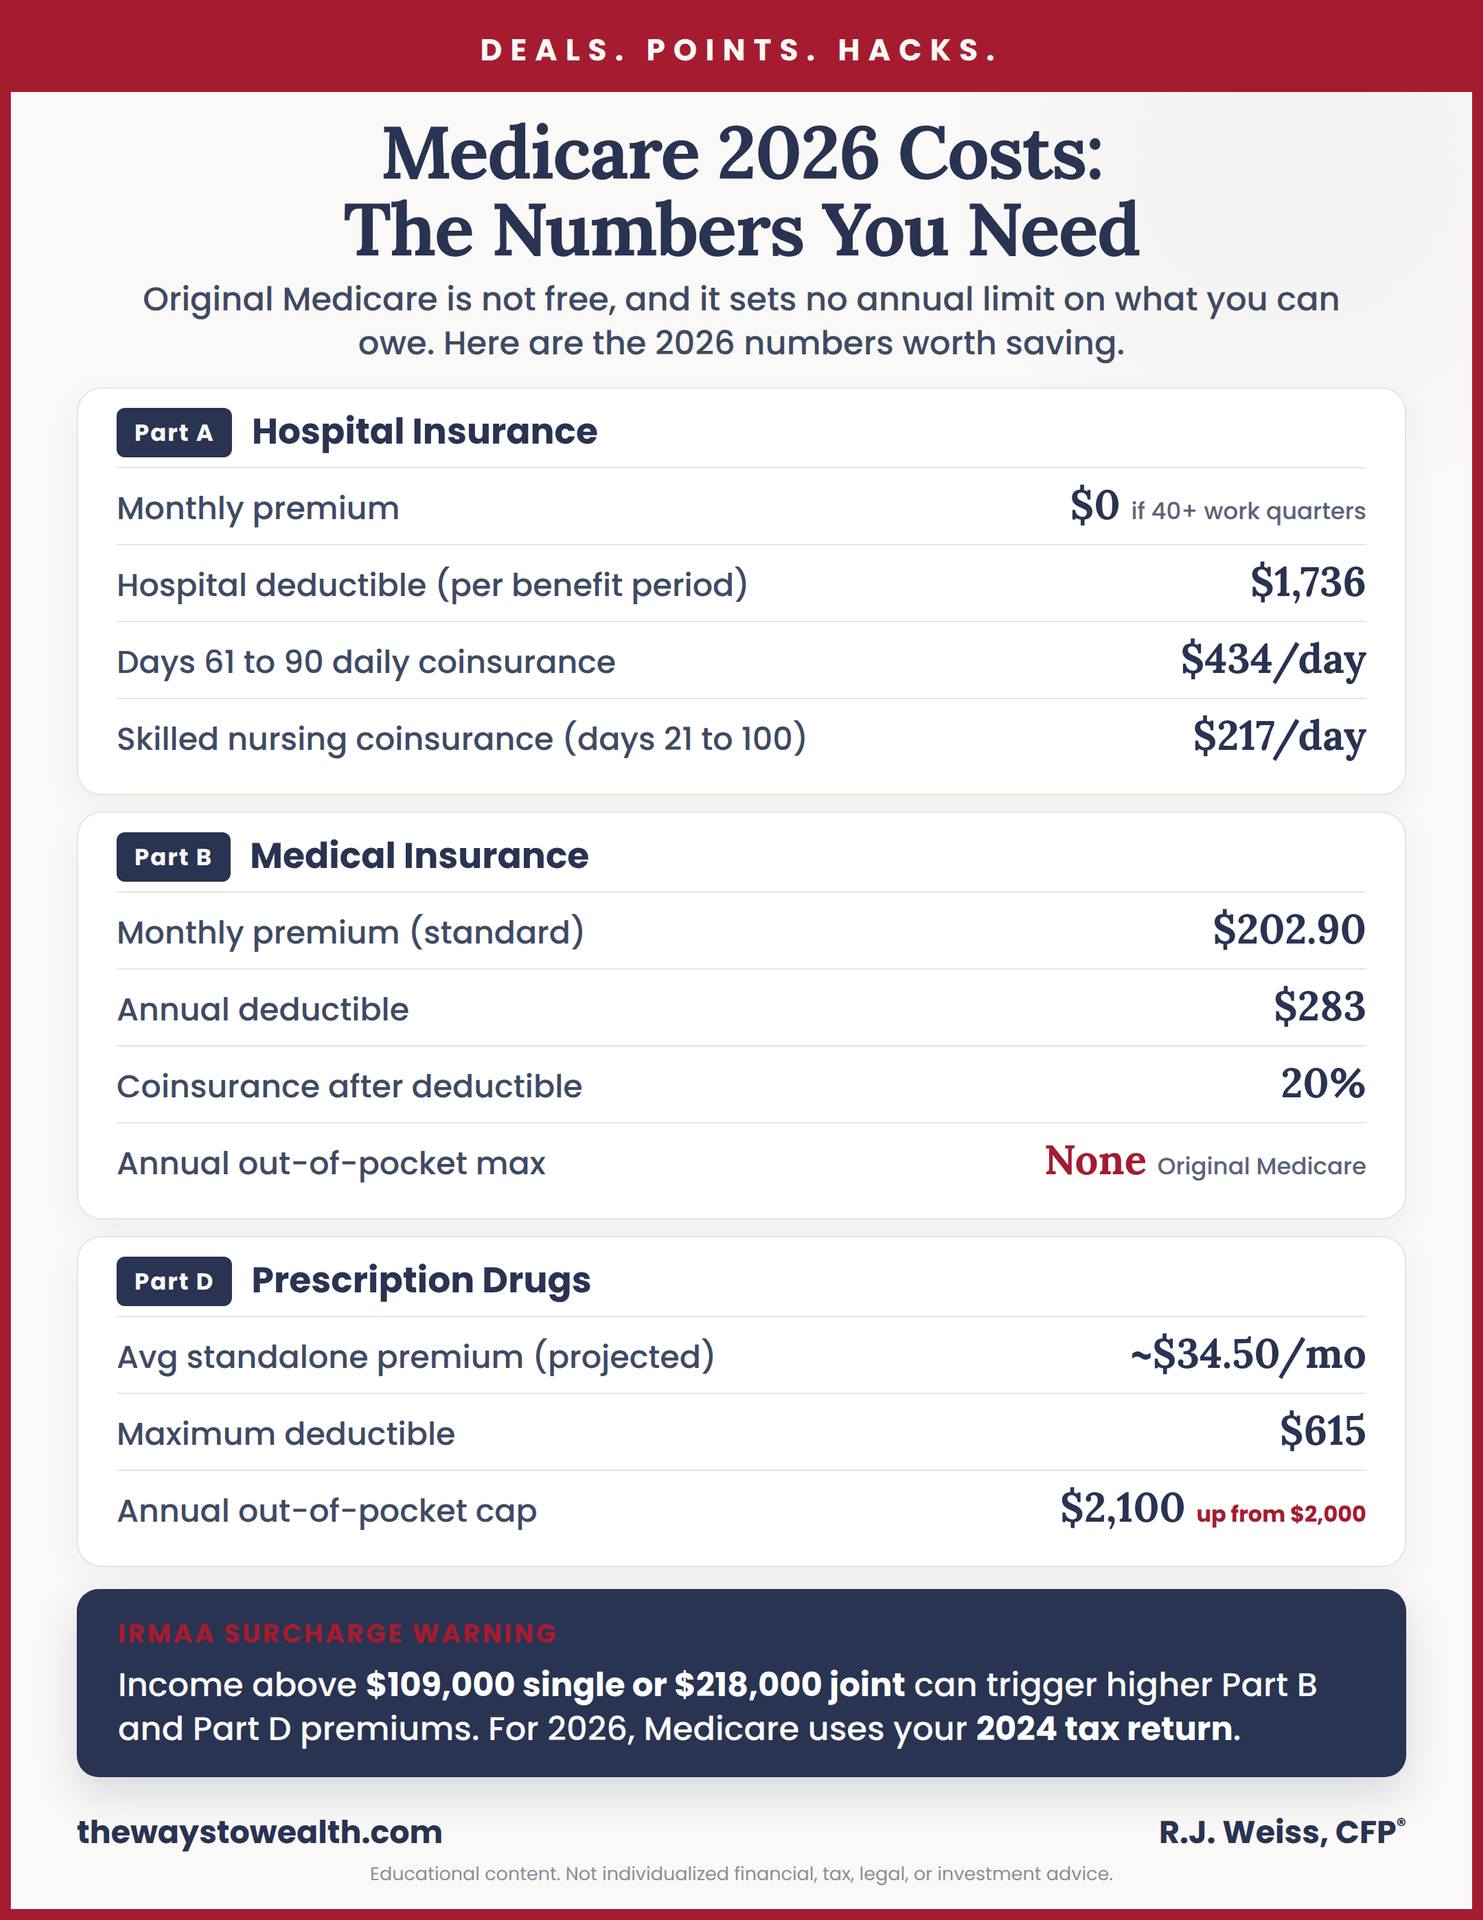
How to Enroll in 2026 Medicare Part D

Choosing Between PPO Vs HMO Medical Plans